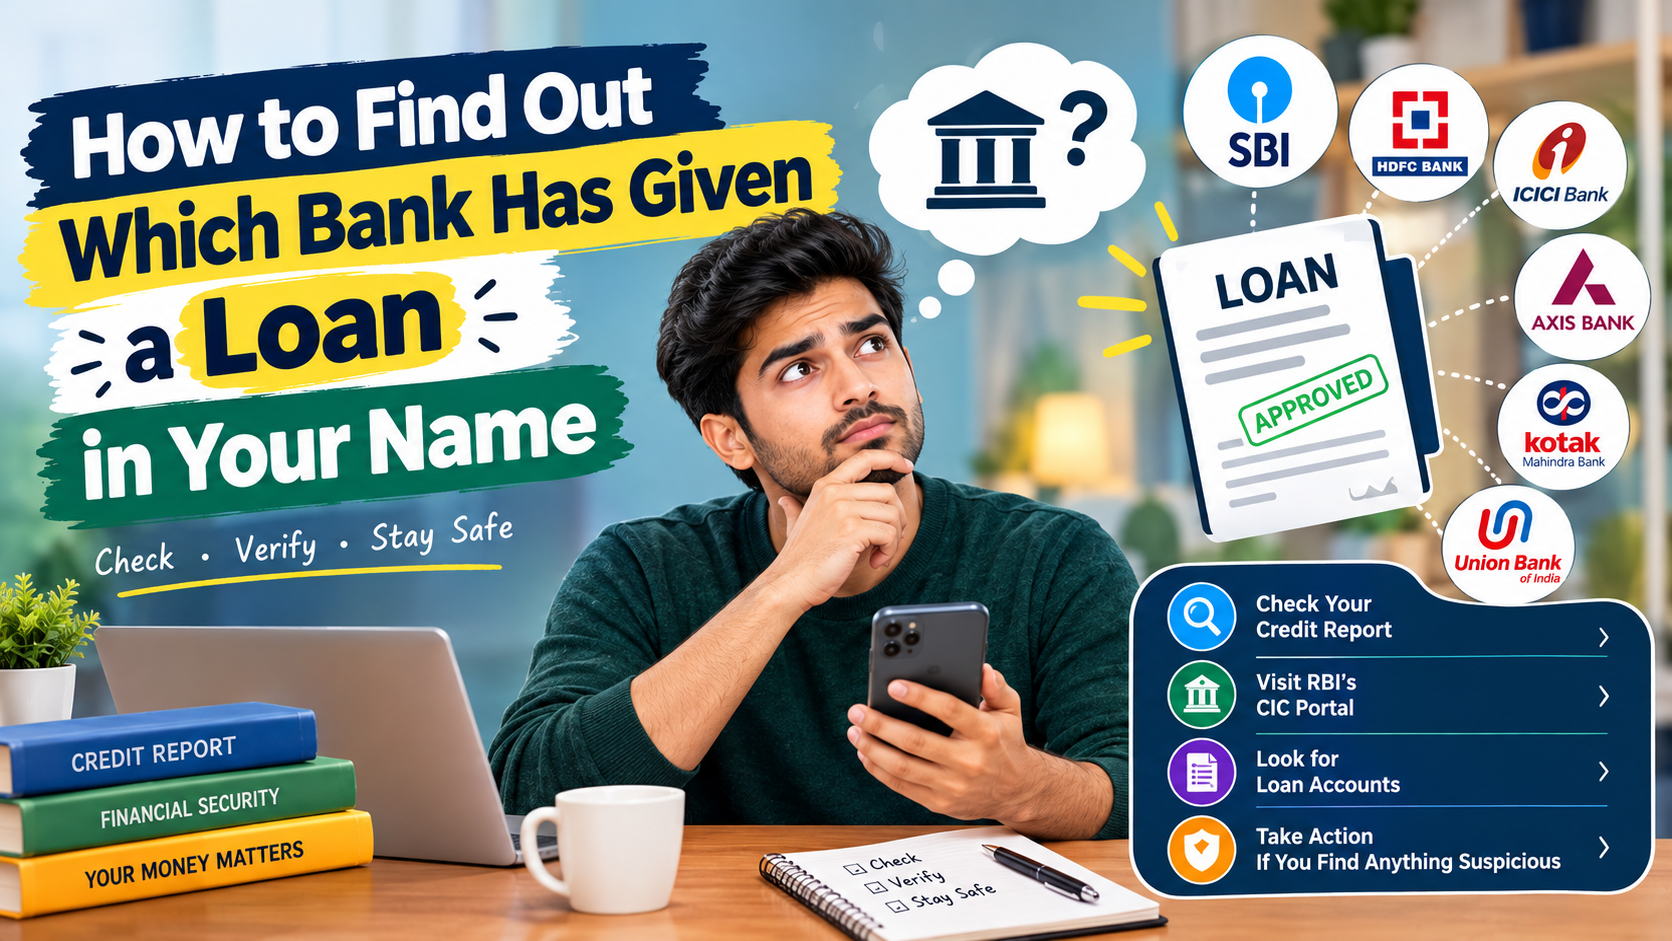
Have you ever checked your credit report and found a loan account you do not recognise? You might see an unfamiliar bank name or an outstanding balance that you never expected.
This situation can be confusing, especially if you do not know where the loan came from. It could be a reporting mistake, an old account, or a sign that someone has misused your personal information.
The good news is that you can investigate most reported loan accounts online. Here is how to find out which bank has given a loan in your name and what to do if something looks incorrect.
Why Should You Check Which Bank Has Given You a Loan?
Knowing which financial institution has reported a loan helps you understand your financial situation and identify possible errors.
Here are a few important reasons to check:
-
Identify unknown loans: Find accounts you do not remember opening.
-
Protect your credit score: Identify incorrect balances or overdue payments.
-
Detect possible fraud: Check whether someone may have misused your personal information.
-
Verify old loans: Make sure repaid loans are correctly marked as closed.
-
Prepare for new credit: Understand your existing debt before applying for another loan.
1. Check Your Credit Report Online
Your credit report is one of the easiest ways to identify banks and financial institutions associated with loans in your name.
Credit bureaus collect information reported by participating lenders. Your report may include personal loans, home loans, vehicle loans, education loans, and credit card accounts.
Steps to check your credit report
-
Visit the official website of a credit bureau.
-
Register or sign in using the required details.
-
Complete the identity verification process.
-
Access your credit report.
-
Open the section showing your credit accounts.
-
Review the lender's name and loan details.
You can start with the official TransUnion CIBIL website.
Check these details carefully:
-
Bank or lender name
-
Loan account number
-
Loan opening date
-
Outstanding balance
-
Payment history
-
Account status
Note: Your credit report shows information reported by participating lenders. Some accounts may take time to appear, so verify important details directly with the lender.
2. Identify the Bank or Financial Institution
Once you find an unfamiliar loan, look at the lender's name listed beside the account.
Sometimes, the name may differ from the brand you remember.
For example, you might have applied for a loan through a digital lending app, but the actual lender could be a bank or a non-banking financial company (NBFC).
How to identify an unfamiliar lender
-
Search your email inbox for loan approval messages.
-
Check SMS messages for repayment reminders.
-
Review old loan agreements and bank statements.
-
Compare the loan account number with your records.
-
Check whether the lender operates under a different legal name.
Do not immediately assume that an unfamiliar bank name means fraud. First, verify the account details.
3. Check Whether the Loan Is Still Active
After identifying the lender, check the account status to understand whether the loan is active or closed.
Pay attention to:
-
Outstanding balance: Check how much the report shows as unpaid.
-
Account status: See whether the loan is marked active or closed.
-
Payment history: Look for missed or overdue payments.
-
Opening date: Confirm when the account was created.
If you want a detailed guide to checking active loans, visit our article on Check Active Loan on My Name.
If you have already repaid a loan but it still appears active, contact the lender and request an update.
4. Contact the Bank Directly
If you cannot identify the loan, contact the bank or financial institution listed in your report.
Use its official customer care number, email address, or grievance redressal channel.
Explain that you do not recognise the account and request an investigation.
Information you may need
-
Your name and required identification details
-
Loan account number from the report
-
Relevant pages of your credit report
-
A clear explanation of the problem
-
Supporting documents, if requested
Ask the lender to verify the loan application and account records.
Keep your complaint reference number and save all communication. These records can help if you need to escalate the complaint later.
Important: Never share your OTP, PIN, or banking password with anyone claiming to investigate a loan.
5. What If Someone Has Taken a Loan in Your Name?
If you never applied for the loan and cannot identify the account, it could be a reporting error or possible identity theft.
Take the following steps:
Contact the lender: Report the unfamiliar account and request a formal investigation.
Raise a dispute: Contact the relevant credit bureau and dispute the incorrect loan information.
Keep evidence: Save your credit report, complaint reference number, emails, and relevant messages.
Report suspected fraud: In India, suspected cybercrime can be reported through the official National Cyber Crime Reporting Portal. If you have lost money due to cyber financial fraud, call the national cybercrime helpline at 1930 as soon as possible.
Do not pay an unfamiliar loan simply because it appears in your report. Ask the lender to investigate and clarify the account first.
6. How Long Does It Take to Resolve the Issue?
The time required depends on the type of complaint and the investigation.
A simple reporting error may be easier to resolve than a suspected fraudulent loan that requires additional verification.
To avoid unnecessary delays:
-
Submit accurate information.
-
Provide requested documents promptly.
-
Keep your complaint reference number.
-
Follow up through official channels.
-
Check your updated credit report after the investigation.
If the issue remains unresolved, escalate it through the lender's grievance redressal process.
Conclusion
Finding out which bank has given a loan in your name starts with checking your credit report. Review the lender's name, account details, and payment history.
If you discover an unfamiliar loan, contact the lender and request an investigation. Raise a dispute with the credit bureau if the information is incorrect.
Regular credit report checks can help you identify errors early, protect your personal information, and maintain an accurate credit history.
Frequently Asked Questions
1. How can I find out which bank has given a loan in my name?
Check your credit report and review the lender's name under your loan accounts. Contact the institution if you need further verification.
2. Can I find a loan using my PAN card?
Your PAN helps identify your credit records. You can use it during the required verification process to access your credit report.
3. What should I do if I do not recognise the lender?
Check your emails and loan documents. If the account remains unfamiliar, contact the lender and request an investigation.
4. Can an unknown loan affect my CIBIL score?
Yes. An unfamiliar loan or its repayment history may affect your credit profile. If the information is incorrect, raise a dispute.
5. How often should I check my credit report?
Check it periodically and before applying for a major loan. Regular reviews can help you identify unfamiliar accounts and reporting errors early.