Retirement is an important milestone, and knowing how to access your savings can help you manage your finances with confidence. If you have been contributing to a Fidelity retirement plan for years, you may wonder how to withdraw your money after leaving your job.
The Fidelity 401k withdraw process allows eligible retirees to access their retirement savings through different withdrawal options. Depending on your employer's plan, you may be able to take a partial withdrawal, receive regular payments, or withdraw your entire available balance.
However, understanding withdrawal rules, income taxes, and payment methods is essential before making a decision. Taking too much money at once may increase your taxable income and reduce the savings available for future expenses.
This guide explains how to withdraw from Fidelity 401k after retirement, including eligibility requirements, online withdrawal steps, taxes, processing times, and common mistakes to avoid.
What Is a Fidelity 401k Withdrawal After Retirement?
A Fidelity 401k withdrawal after retirement means taking money from an employer-sponsored retirement savings plan after leaving the workforce.
A 401(k) is a retirement account that allows employees to save and invest money for the future. Fidelity Investments provides recordkeeping and account management services for many employer-sponsored retirement plans.
After retirement, you may have several options for accessing your savings.
These options may include:
-
Taking a one-time withdrawal
-
Requesting partial withdrawals
-
Receiving scheduled retirement payments
-
Withdrawing your entire vested balance
-
Rolling eligible savings into an IRA
Available distribution options depend on your employer's plan rules. Some plans offer more flexibility than others.
How To Withdraw From Fidelity 401k After Retirement: Step-by-Step Guide
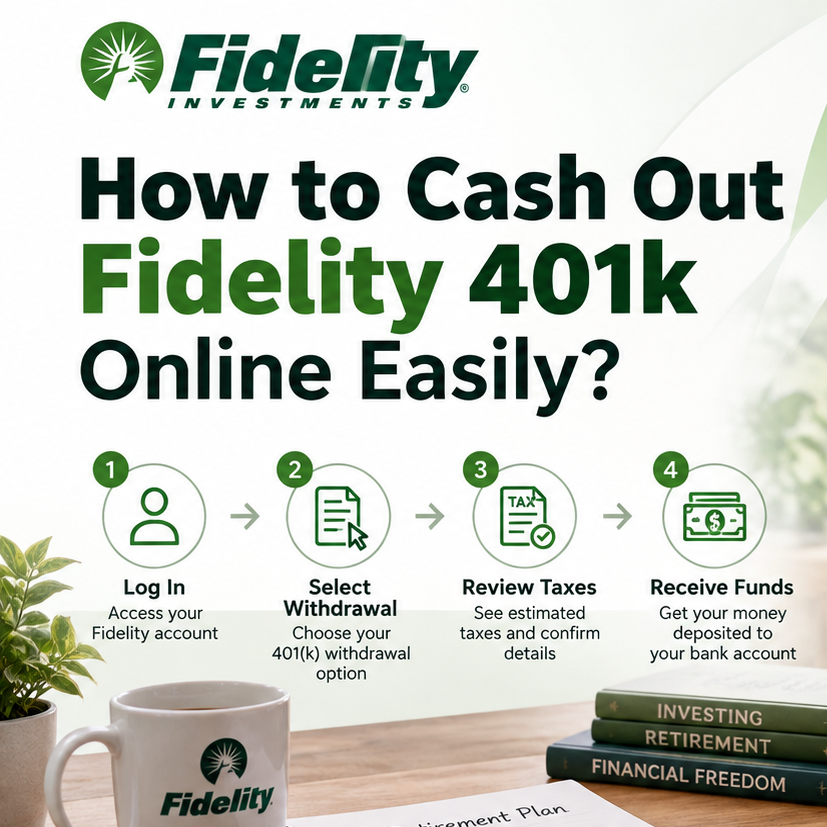
If you are searching for how to take money out of 401k Fidelity, the process usually begins with your Fidelity NetBenefits account.
Follow these steps to review your retirement withdrawal options.
Step 1: Log In to Your Fidelity Account
Visit the official Fidelity NetBenefits website and sign in using your registered username and password.
Once logged in, select your employer-sponsored 401(k) account.
Review your available account balance and check whether your retirement status has been updated.
Step 2: Check Your Withdrawal Eligibility
Before submitting a Fidelity Investments 401k withdrawal request, confirm that your plan allows distributions.
Eligibility may depend on:
-
Your current age
-
Your employment status
-
Your vested account balance
-
Your employer's plan rules
-
The withdrawal option you select
Retirement or separation from employment generally creates an opportunity to access vested retirement savings, although individual plan restrictions may apply.
Step 3: Open the Withdrawal Section
Select your retirement plan and navigate to the section for loans, rollovers, and withdrawals.
Review the available options and choose the type of distribution you want to request.
Fidelity confirms that eligible participants can review withdrawal options through NetBenefits.
Step 4: Choose Your Withdrawal Amount
Decide how much money you want to withdraw.
Depending on the plan, you may request a partial withdrawal, periodic payments, or a full distribution.
A smaller withdrawal may help preserve funds for future retirement expenses.
Step 5: Select Your Payment Method
Choose an available payment option.
Depending on your plan, payment methods may include:
-
Electronic deposit into an eligible bank account
-
A check mailed to your registered address
Confirm your banking information and mailing address before proceeding.
Step 6: Review Taxes and Submit Your Request
Review the withdrawal amount, federal and state tax withholding, and any applicable fees.
Follow the instructions to submit your request and save the confirmation details.
You can check the payment status through your account or contact Fidelity retirement support if additional assistance is needed.
Fidelity 401k Withdrawal Rules After Retirement
Understanding Fidelity 401k withdrawal rules can help you avoid unexpected taxes and payment restrictions.
Withdrawals After Age 59½
If you are at least 59½ years old, withdrawals from a 401(k) generally are not subject to the additional 10% federal early distribution tax.
However, withdrawals from a traditional pretax 401(k) are usually subject to ordinary income tax.
For example, if you retire at age 65, you may withdraw eligible savings without the 10% early withdrawal tax, but the taxable amount generally remains part of your annual income.
Withdrawals Before Age 59½
A Fidelity 401k early withdrawal may be subject to an additional 10% tax unless an IRS exception applies.
One important exception applies to certain distributions from an employer's plan after separating from service during or after the calendar year you turn 55.
This exception has specific requirements and generally does not apply to withdrawals from an IRA.
Required Minimum Distributions
The IRS generally requires retirees to begin taking required minimum distributions (RMDs) from traditional retirement accounts after reaching the applicable age.
Under current rules:
-
Individuals born from 1951 through 1959 generally begin RMDs at age 73.
-
Individuals born in 1960 or later generally begin RMDs at age 75.
-
Some employees who continue working may qualify to delay workplace-plan RMDs.
-
Designated Roth 401(k) accounts do not require lifetime RMDs for the original account owner.
Your first distribution deadline and payment amount depend on your age and circumstances.
How Much Tax Will You Pay on a Fidelity 401k Withdrawal?
Taxes are an important consideration when planning retirement withdrawals.
Money withdrawn from a traditional pretax 401(k) is generally treated as taxable income.
Your actual tax liability depends on your total income, filing status, applicable deductions, and state tax rules.
For example, suppose you withdraw $20,000 from a traditional Fidelity 401(k).
If the distribution is eligible for rollover but is paid directly to you, mandatory federal withholding is generally 20%, or $4,000.
You would initially receive $16,000 before any other applicable deductions. However, the withholding amount is not necessarily your final income tax.
Other withdrawal types, including periodic payments and RMDs, follow different withholding rules.
Fidelity 401k Cash Out vs. Partial Withdrawal
Many retirees consider a Fidelity 401k cash out because they want immediate access to their retirement savings.
However, withdrawing your entire account balance may not always be necessary.
Full 401k Cash Out
A full cash-out means withdrawing your entire available vested account balance.
It may provide immediate access to a substantial amount of money, but it can also create a larger taxable distribution and eliminate the money's future tax-deferred growth.
Partial 401k Withdrawal
A partial withdrawal allows you to take out a smaller amount while leaving the remaining savings invested.
Possible advantages include:
-
Keeping some retirement funds invested
-
Managing annual taxable income
-
Covering planned expenses
-
Preserving savings for later retirement years
Your employer's plan determines whether partial withdrawals are available.
Can You Withdraw Fidelity 401k After Leaving Your Employer?
Yes. A Fidelity 401k withdrawal after leaving employer arrangements generally becomes available when you separate from service, subject to the plan's distribution rules.
For individuals researching withdrawing 401k after leaving job Fidelity, retirement creates several possible choices.
You may:
-
Keep your account in the former employer's plan, if permitted.
-
Roll over eligible funds into a traditional or Roth IRA, following applicable tax rules.
-
Transfer savings into another eligible employer retirement plan.
-
Take an eligible taxable cash distribution.
A properly completed direct rollover of pretax 401(k) funds to a traditional IRA generally does not create immediate federal income tax.
What About Fidelity Individual 401k and Self-Employed Plans?
A Fidelity Individual 401k is designed for eligible self-employed individuals and business owners without employees other than a spouse.
People searching for self employed 401k Fidelity or personal 401k Fidelity withdrawal information should understand that these plans may have different administration procedures.
Although federal retirement distribution rules generally apply, withdrawal paperwork, plan responsibilities, and available options may differ from those of a traditional employer-sponsored Fidelity 401(k).
Review the specific plan documents before requesting funds.
Can You Request a Fidelity 401k Hardship Withdrawal After Retirement?
A Fidelity 401k withdrawal hardship option is generally intended for qualifying financial needs under an employer's plan.
After retirement or separation from employment, you may already qualify for a regular distribution without needing to establish financial hardship.
Therefore, a standard retirement withdrawal may be more appropriate than a hardship request.
Remember that hardship distributions are generally taxable when taken from pretax funds, may trigger an early withdrawal tax, and cannot be rolled over.
How Long Does Fidelity Take to Process a 401k Withdrawal?
The time required to process a retirement withdrawal depends on your plan, payment method, and any verification requirements.
Electronic transfers may be faster than receiving a paper check.
Common reasons for delays include:
-
Incomplete withdrawal information
-
Incorrect bank account details
-
Employer retirement status updates
-
Additional identification requirements
-
Plan-specific distribution approvals
Check your Fidelity account for the processing estimate associated with your request rather than assuming a fixed delivery time.
Common Mistakes to Avoid When Withdrawing Fidelity 401k
Withdrawing retirement savings requires careful planning.
Some common mistakes include:
-
Withdrawing the entire balance without calculating taxes
-
Ignoring required minimum distribution rules
-
Assuming retirement automatically makes every withdrawal tax-free
-
Choosing a payment method without checking the details
-
Forgetting to update personal or banking information
-
Failing to consider future living and medical expenses
Review your financial needs and retirement income before making a large withdrawal.
Frequently Asked Questions
1. How do I withdraw money from Fidelity 401k after retirement?
Log in to Fidelity NetBenefits, select your workplace retirement account, and review the available withdrawal options. Choose an eligible distribution, enter the required information, review taxes, and submit your request.
2. Can I withdraw all my Fidelity 401k money after retirement?
Yes, many retirement plans allow eligible participants to withdraw their entire vested balance after retiring. However, the availability of a full distribution depends on the specific plan, and taxes may apply.
3. Is Fidelity 401k withdrawal tax-free after age 65?
No. Traditional pretax 401(k) withdrawals are generally subject to income tax, even after age 65. However, the additional 10% early withdrawal tax usually does not apply after age 59½. Qualified Roth 401(k) distributions may be tax-free.
4. Can I withdraw Fidelity 401k money online?
Yes, many Fidelity workplace retirement plans allow eligible participants to initiate withdrawals through NetBenefits. Some requests may require additional documentation or assistance.
5. What happens if I leave my Fidelity 401k untouched after retirement?
Your money may remain invested if the former employer's plan permits you to keep the account. However, required minimum distributions eventually apply to traditional 401(k) balances, based on your applicable starting age.
6. Can I transfer my Fidelity 401k into a bank account after retirement?
Yes, eligible cash distributions may be sent to a linked bank account if your plan offers electronic payment. The taxable portion may be subject to withholding and income taxes.
Conclusion
Understanding how to withdraw from Fidelity 401k after retirement can help you access your retirement savings while making informed financial decisions.
The Fidelity 401k withdraw process generally involves logging in to NetBenefits, reviewing eligibility, choosing a distribution option, confirming payment information, and submitting your request.
Before taking money out, consider the potential tax impact, your future retirement expenses, and whether you need a full withdrawal or only a smaller amount.
A thoughtful withdrawal strategy can help you manage retirement income while preserving savings for the years ahead.