1. Is a Construction Equipment Loan Calculator Useful for First-Time Equipment Buyers?
Buying construction equipment for the first time can be an exciting step for any business owner. Whether you are starting a construction company, expanding your services, or taking on larger projects, the right equipment can help you complete work more efficiently. However, construction machinery can be expensive, and paying the full price upfront may not be possible for every business.
Many first-time buyers consider financing to spread the cost of equipment over several months or years. Before choosing a financing option, it is important to understand the expected monthly payments, interest costs, and total amount you may need to repay. Without proper planning, equipment payments can put pressure on your business budget.
A construction equipment loan calculator can help you understand these costs before making a decision. It allows you to estimate payments, compare different financing terms, and plan your spending more carefully.
For business owners exploring financing options, Smart Business Credit can be a starting point for learning about business credit and preparing for equipment-related financial decisions.
What Is a Construction Equipment Loan Calculator?
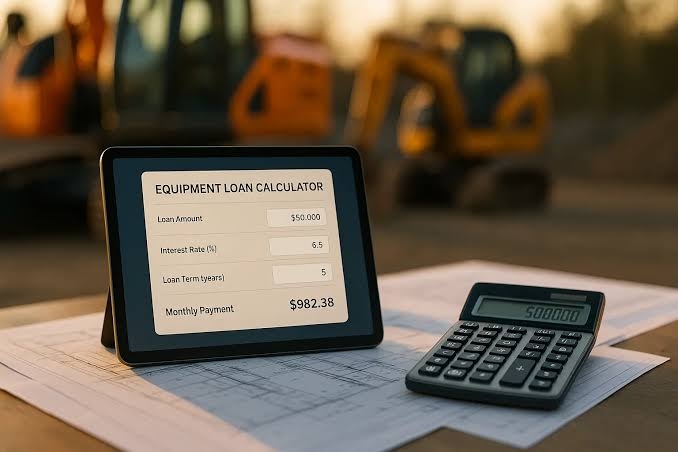
A construction equipment loan calculator is a financial tool that helps you estimate the cost of borrowing money to purchase construction machinery. You enter details such as the loan amount, interest rate, and repayment period to calculate an estimated monthly payment.
For example, suppose you want to purchase a piece of construction equipment worth $50,000. You have enough savings to make a down payment, but you need financing for the remaining cost. By entering the amount you want to borrow and the expected loan terms, you can estimate how much you may need to pay each month.
This information helps you understand whether the financing fits your business budget. It can also help you compare different repayment periods before choosing an option.
The calculator does not guarantee loan approval or confirm the exact terms a lender will offer. Instead, it gives you an estimate that can support your financial planning.
Why Is a Construction Equipment Loan Calculator Useful for First-Time Buyers?
First-time equipment buyers may not have much experience comparing financing options. They may understand the price of a machine but have less knowledge of how interest rates, repayment periods, and fees affect the final cost.
A construction equipment loan calculator makes these details easier to understand. Instead of guessing your monthly payments, you can enter different figures and see how the estimated costs change.
For example, you can compare a shorter repayment period with a longer one. You can also test different down payment amounts to see how borrowing less money may affect your payments.
This process helps you prepare questions for a financing provider and understand your financial responsibilities before signing an agreement.
For new construction businesses, planning ahead is especially important because equipment payments must fit alongside fuel, maintenance, employee wages, insurance, and other operating expenses.
How Does the Calculator Help You Estimate Monthly Payments?
Monthly payments are one of the most important parts of an equipment financing decision. They determine how much money you must set aside regularly to repay the borrowed amount.
A construction equipment loan calculator uses your loan details to estimate these payments. The main information usually includes the amount borrowed, the interest rate, and the repayment period.
For example, imagine you need to borrow $40,000 to purchase construction machinery. You can enter this amount into the calculator and test different repayment periods to understand how the estimated monthly payments change.
A shorter repayment period generally means higher monthly payments because the debt must be repaid more quickly. A longer repayment period may reduce the monthly payment, but it can increase the total interest paid over the life of the loan.
Knowing these differences helps first-time buyers choose a payment schedule that is more suitable for their expected income and regular business expenses.
How Can It Help You Set a Realistic Equipment Budget?
Buying construction equipment involves more than paying for the machine itself. You may also need to pay for transportation, fuel, repairs, insurance, storage, and regular maintenance.
If you spend too much on loan payments, you may not have enough money left to cover these other expenses. This can create problems when your business faces unexpected costs or experiences a slow period.
A construction equipment loan calculator helps you estimate your potential monthly payment before committing to a purchase. You can then compare that payment with your expected business income and operating costs.
For example, if your business can comfortably allocate a certain amount each month to equipment financing, you can adjust the loan amount and repayment period to explore options that fit your budget.
It is also wise to keep some money available for emergencies. Construction work may not generate the same income every month, so your budget should allow for changes in project schedules and customer payments.
Can It Help You Compare Different Financing Options?
Yes, comparing financing options is one of the main benefits of using a construction equipment loan calculator.
Different financing offers may have different interest rates, repayment periods, down payment requirements, and fees. Even when two options appear similar, their total costs may be different.
You can use the calculator to compare these options by entering the details of each offer separately.
For example, one financing option may offer a lower interest rate but require a shorter repayment period. Another may allow a longer repayment period but charge a higher rate. Comparing the estimated monthly payments and total repayment amounts helps you understand the financial differences.
However, do not choose a financing option based only on the smallest monthly payment. Consider the total borrowing cost and whether the payment schedule works with your business income.
You should also review the complete financing agreement to understand any additional charges or special conditions.
How Does the Down Payment Affect Your Loan?
A down payment is the amount you pay upfront toward the equipment purchase. The remaining amount may be covered through financing.
A larger down payment usually means you need to borrow less money. When the interest rate and repayment period remain the same, borrowing less generally reduces monthly payments and total interest costs.
For example, suppose a machine costs $60,000. If you pay $10,000 upfront, you may need to finance $50,000 before fees and other charges.
If you can pay $15,000 upfront, the amount you need to borrow falls to $45,000.
A construction equipment loan calculator can help you compare the estimated payments for both situations.
However, using more savings for a down payment leaves less cash available for other business needs. First-time buyers should consider how much money they need to keep available for wages, fuel, maintenance, and unexpected expenses before deciding how much to pay upfront.
What Types of Construction Equipment Can You Plan to Finance?
Construction businesses use many types of equipment to complete projects. The cost of each machine depends on its size, condition, features, and intended use.
A construction equipment loan calculator can help you estimate financing costs for purchases such as excavators, bulldozers, loaders, cranes, skid steers, and other machinery.
It may also be useful when planning to finance work vehicles or smaller equipment needed for daily construction tasks, depending on the financing arrangement.
Before using the calculator, determine the equipment you need and its expected purchase price. You should also consider whether buying new or used equipment makes more sense for your business.
New equipment may offer updated features and warranty coverage, while used equipment may have a lower purchase price. However, used machinery may require more repairs or maintenance.
Comparing the financing costs alongside the expected operating costs can help you make a more informed purchasing decision.
What Information Do First-Time Buyers Need Before Using the Calculator?
To get useful results, collect the basic details of your planned equipment purchase.
First, identify the equipment's purchase price and determine how much money you can pay upfront. This helps you estimate the amount you need to borrow.
Next, review any financing offers you have received. If you know the interest rate and repayment period, enter those details into the calculator. If you do not have an offer yet, you can test different figures to understand how payments might change.
You should also check whether the financing provider charges fees or requires a final payment. Some calculators do not include these costs in their estimates, so you may need to account for them separately.
Finally, review your business budget. Consider your expected income, regular operating costs, existing debt payments, and the money you need for emergencies.
Using accurate information makes the results more helpful and gives you a clearer picture of the financial commitment involved.
Common Mistakes First-Time Equipment Buyers Should Avoid
One common mistake is focusing only on the equipment's purchase price. The full cost of owning machinery can include financing charges, insurance, fuel, storage, repairs, and maintenance.
Another mistake is choosing the longest repayment period simply because it produces lower monthly payments. While this may improve short-term cash flow, it can increase the total interest paid.
Some buyers also assume that the calculator's results are guaranteed. In reality, the final financing terms depend on the provider's assessment and the agreement offered.
It is also important to avoid borrowing more than your business needs. Expensive equipment may seem attractive, but a larger loan can create unnecessary financial pressure if a less expensive machine can complete the required work.
Before signing a financing agreement, compare your options, review the terms carefully, and make sure the expected payments fit your business budget.
How Can Smart Business Credit Help You Prepare for Equipment Financing?
Preparing for equipment financing involves understanding your business finances and knowing what lenders may consider when reviewing an application.
Business owners should review their credit profile, organize relevant financial records, and develop a realistic budget before applying for financing. These steps can help them understand their financial position and prepare for questions about their borrowing needs.
Smart Business Credit provides a relevant starting point for business owners who want to learn more about business credit and financing considerations.
Using a construction equipment loan calculator alongside careful financial planning can help you understand potential payments before making a commitment. You can compare different loan amounts, test repayment periods, and identify options that may fit your business requirements.
Remember that a calculator cannot guarantee approval, a specific interest rate, or a particular financing offer. It is a planning tool that helps you prepare for a more informed discussion about financing.
Conclusion
A construction equipment loan calculator can be very useful for first-time equipment buyers. It helps estimate monthly payments, compare financing options, understand the effect of down payments, and plan a realistic equipment budget.
By testing different loan amounts, interest rates, and repayment periods, you can see how each decision may affect your business finances. This makes it easier to understand the potential cost of purchasing machinery before you commit to a financing agreement.
- Goth Lifestyle
- Fashion & Style
- Music & Bands
- Art & Photography
- Creative Writing & Poetry
- Events & Scene
- Occult & Spirituality
- DIY & Tutorials
- Beauty & Self-Care
- Relationships & Dating
- Gaming & Media
- Tech & Gadgets
- Body Art & Piercings
- Underground Culture
- Spotlights & Interviews
- Travel & Places
- Lifestyle & Daily Life
- Fitness & Health
- Travel & Adventure
- Books & Literature
- Tech & Gaming
- Movies & TV
- Food & Drinks
- Humor & Memes
- Pets & Animals
- General Arts & Crafts

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek